Day 124
It's been a while since I wrote my last post.
Six weeks since Day 123, and I lost nearly all of my profits. My NDX bets lost $7,162 on 25 trades. And non-index positions held longer than seven days lost $6,571 on 15 trades. The only positive - SPX Zero DTE made $3,689 on 71 trades over the same stretch.
This week was close to flat. I closed 34 trades and 22 of them won, but a net loss of -$120. The morning Iron Condors won 8 of 9. Thursday afternoon, between 12:18 and 12:21 PM, I put on four bearish SPX positions that lost $1,758 together.
Portfolio Status
Here is the portfolio status, including unrealized Profit/Loss. My current net liquidity is ~$59,644, up from ~$59,308 at Day 123. I deposited some capital but overall lost about -$6,664.
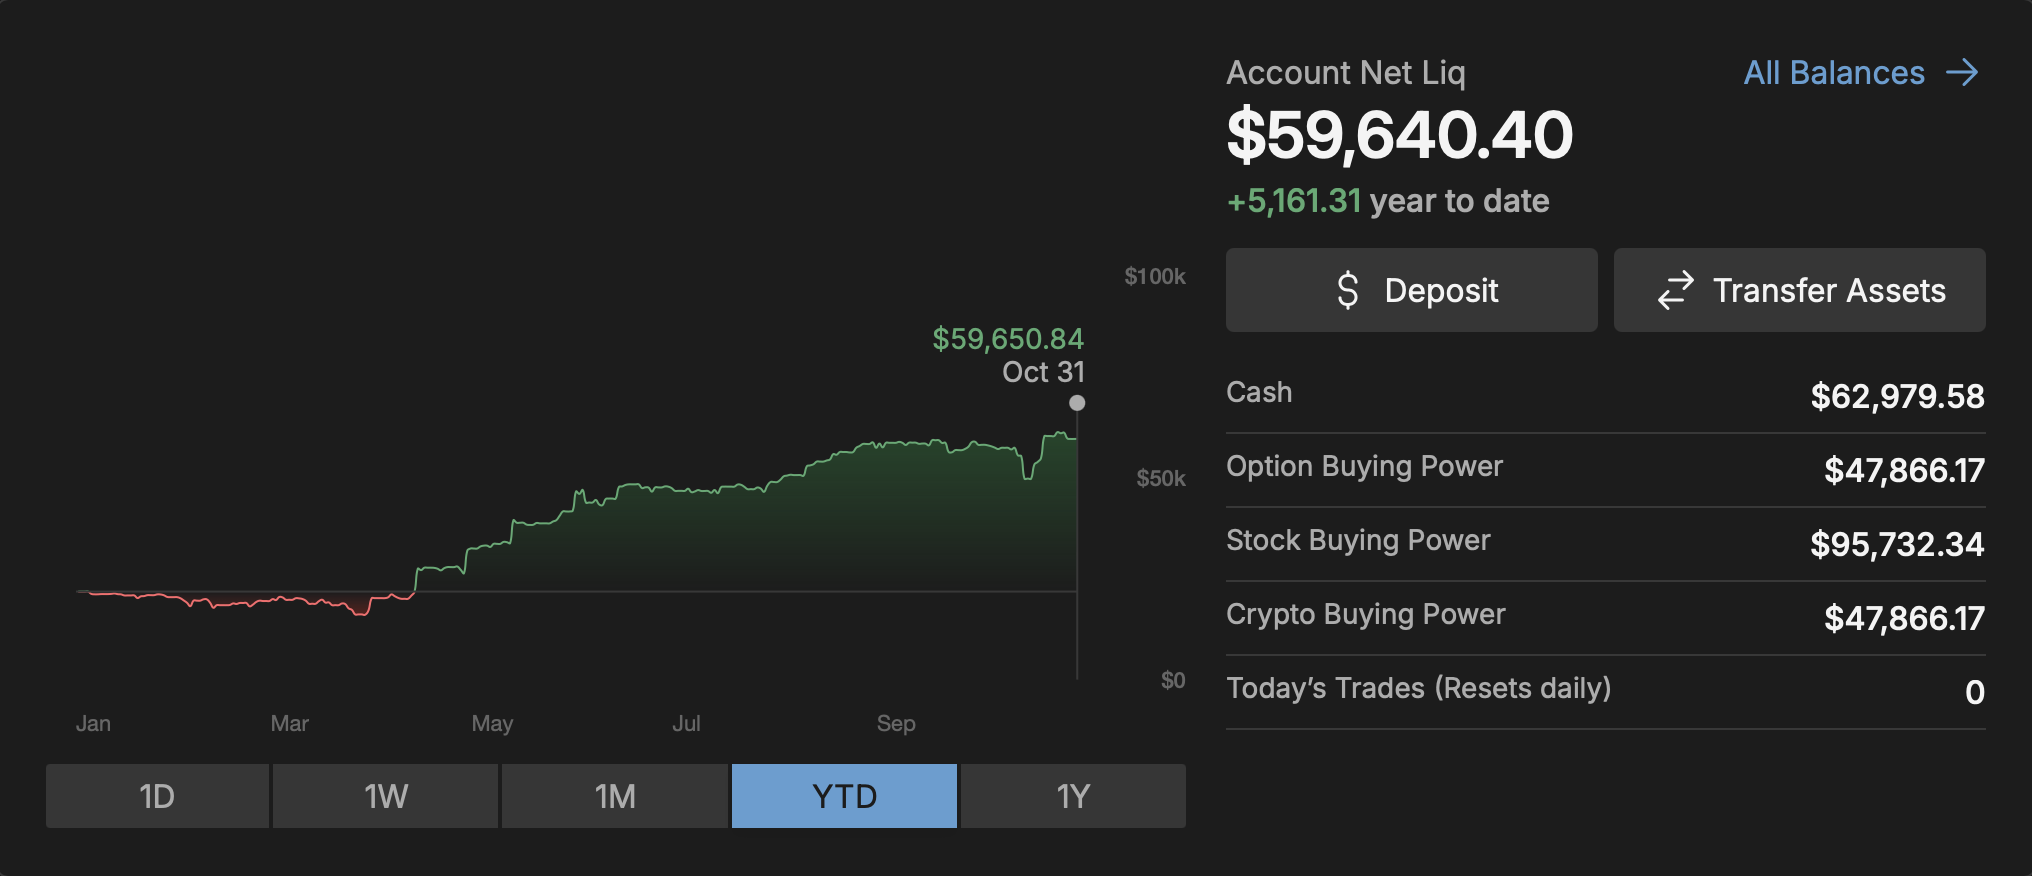
My overall realized gains for the year are $6,947 gross, down from $14,706 at Day 123. Sort the card by "Since Day 123" to see what changed since my last write-up.
Year-to-date P/L by symbol. Open this post on the web to sort and expand the full list.
Details: $6,947 realized, minus $1,820 of unrealized losses on positions I still hold, minus $3,295 of commissions and fees for the year, leaves $1,833. It was $8,535 on Day 123.
The Week at a Glance
Zero DTE made $408 on 22 trades. The Iron Condors made $1,154, the Thursday afternoon positions lost $1,758, and the other Zero DTE trades made $1,012. Longer Dated Index lost $950, almost all of it on one SPX position that expired Wednesday.
Here is the same figure for all six weeks since Day 123, including the SOFI shares I sold on Sep 21:
Closed trades since Day 123 add up to -$9,314 after fees. That is worse than the -$6,664 from net liquidity because some of those losses, the SOFI shares in particular, were already sitting in my net liquidity at Day 123. By week, the six weeks went -$6,459, +$1,745, -$938, -$3,240, -$304 and -$120. Inside Zero DTE, SPX made $3,689 on 71 trades and NDX lost $6,649 on 20.
What I Got Wrong
NDX, minus $7,162 since Day 123. It peaked on Sep 18, the last day Day 123 covered, after 11 wins in 12 trades. Since then I have closed 25 NDX trades and won 10. The worst single trade was Oct 16, when an NDX Put Credit Spread lost $1,583. I closed one NDX trade this week, a Call Credit Spread on Thursday for $112.
Single names I held past seven days, minus $6,571. Since Day 123, single-name trades I closed within seven days went 40 for 44 and made $1,936. The 15 I held longer won 5 times and lost $6,571. The biggest piece was Tuesday Oct 20, when I bought back four Nov 20 naked puts I had been sitting on for 11 to 14 days. BE lost $2,516, CRWV $1,141, INTC $447 and HOOD $437, for $4,542 in one session.
Thursday afternoon, minus $1,758 in three minutes. At 12:18 PM I bought the 7715/7705 Put Debit Spread for $7.80 and sold the 7705/7710 Call Credit Spread for $1.65. At 12:19 I bought the 7700/7695 Put Debit Spread for $1.30, and at 12:21 I rolled its long put up to 7710 for $4.90 more. Every piece needed SPX to fall into the close. SPX settled above 7715 and all three positions lost their full risk. The $7.80 debit on its own needs a 78% win rate to break even. Together they risked about $1,735, four times what I usually put into the afternoon trade.
Monday's Oct 28 combo, minus $987. At 11:07 AM on Oct 26 I sold the Oct 28 7710/7720 Call Credit Spread and bought the 7625/7605 Put Debit Spread for a $0.30 credit. It was another bet on SPX going lower. SPX settled above 7720 on Wednesday and the call side lost the full width.
What I Learned
The morning Iron Condor has routinely proved successful. Nine this week, eight winners, $1,154. Since Day 123 it is 25 winners in 30 trades for $2,675. The one loser this week was Tuesday's 10-wide condor, 7715/7725 calls and 7680/7670 puts, which I held into settlement for -$307. The 15-wide condors went 8 for 8.
The afternoon debit spread is really a gamble with no statistical edge. Since I started on Aug 26, it has won on 18 of 26 days for $2,867. This week Monday was a wash at -$18, Tuesday and Wednesday made $302 and $415, and Thursday lost $721. My average debit is $436 on a 10-wide spread, which breaks even at about a 44% win rate. My two largest debits since I started were $985 on Oct 15 and $780 this Thursday, and they are also my two largest losses on this trade, -$988 and -$783.
The Trades
As usual, all times are Pacific. Risk is the possible maximum loss, which is spread width minus premium received. P/L on each card is after commissions and fees. The cards cover this week only. The heatmap at the end covers September and October.
Zero DTE
Twenty-two trades, fifteen winners, $408.
Every day opened with an Iron Condor before 7:00 AM, and every condor except Tuesday's 10-wide one finished a winner. Friday's three condors made $556 on the day SPX fell 1.8%. The 7585/7570 put side of the third one was tested into the close, and it settled for $20.
Longer Dated Index
Three trades, one winner, -$950.
The Oct 28 combo is in What I Got Wrong. The 7865/7875/7900 Call Broken Wing Butterfly I sold on Oct 21 for $2.75 came off Friday for $2.95.
Futures
Four trades, two winners, $106.
All four were /NQ Put Credit Spreads, and I closed all four on Monday.
Defined Risk Equity Spreads
Two trades, two winners, $258.
Undefined Risk
Three trades, two winners, $58.
Interactive P/L heatmap. Open this post on the web to see the day-by-day breakdown for September and October.
Market Recap
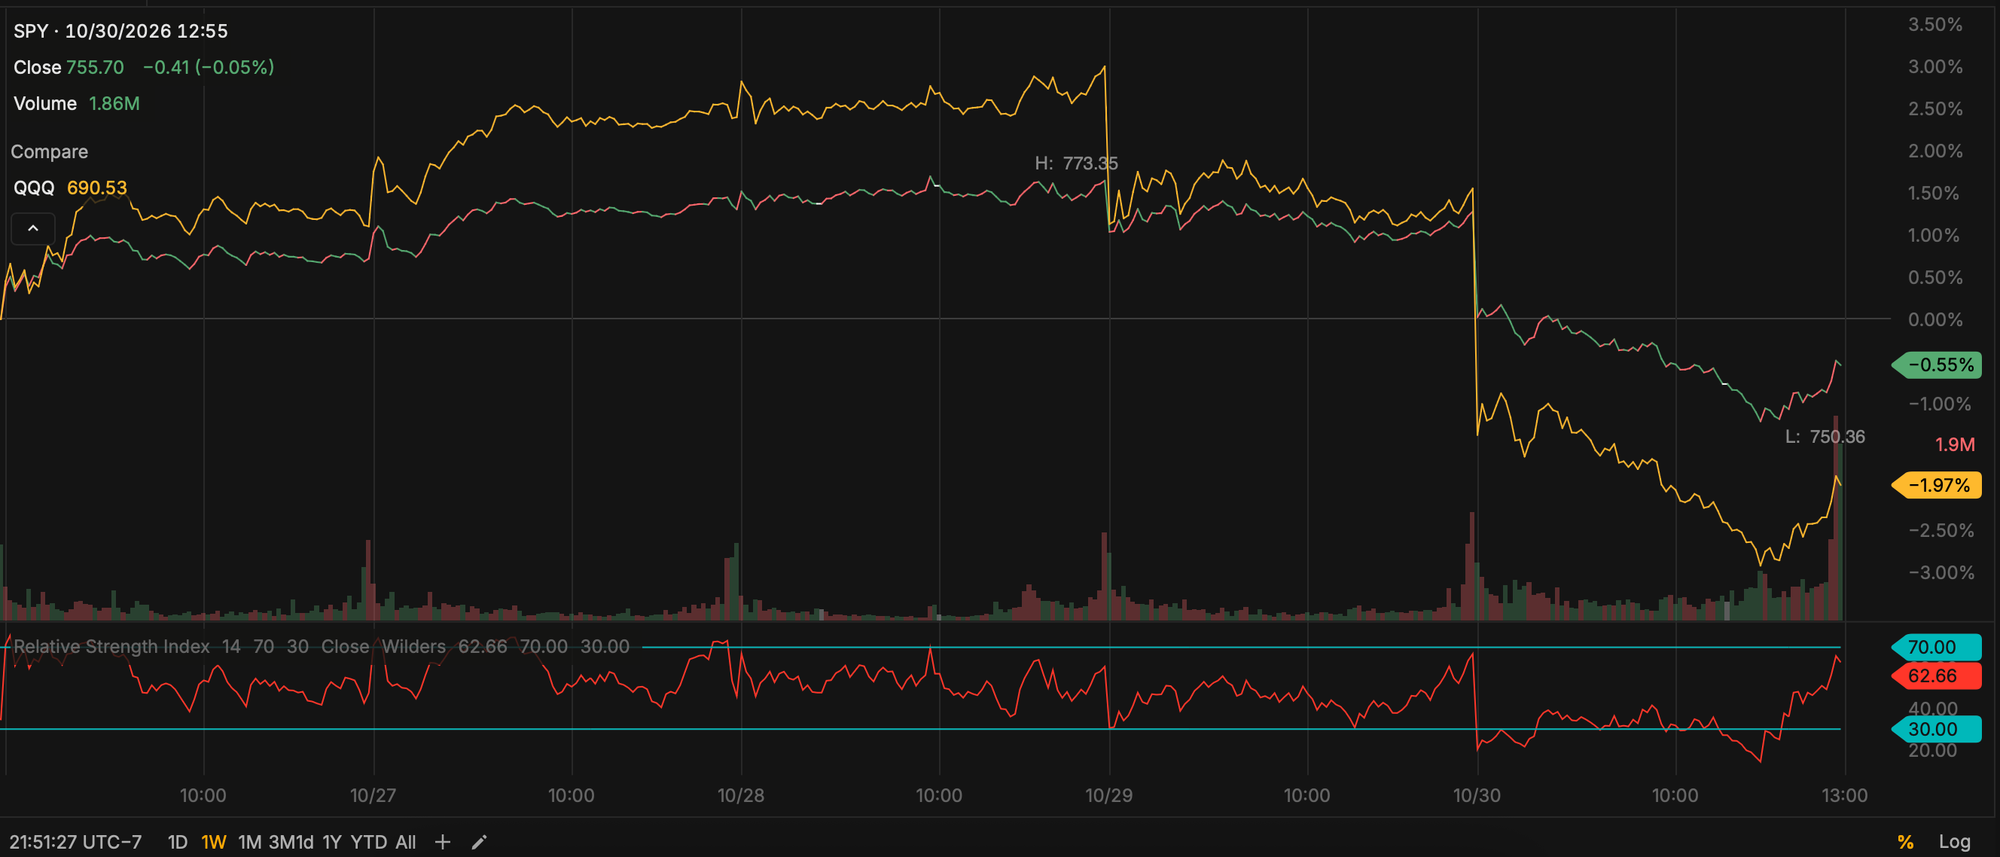
SPY is at ~$756, and QQQ is at ~$690. This week SPY climbed from $759.97 to $772.31 by Wednesday, then gave it all back, closing Friday down 1.8%. Since Day 123, SPY is down about 0.8% and QQQ about 4.3%.
VIX is at 19.42, up from 14.81 at Day 123.
Current Positions
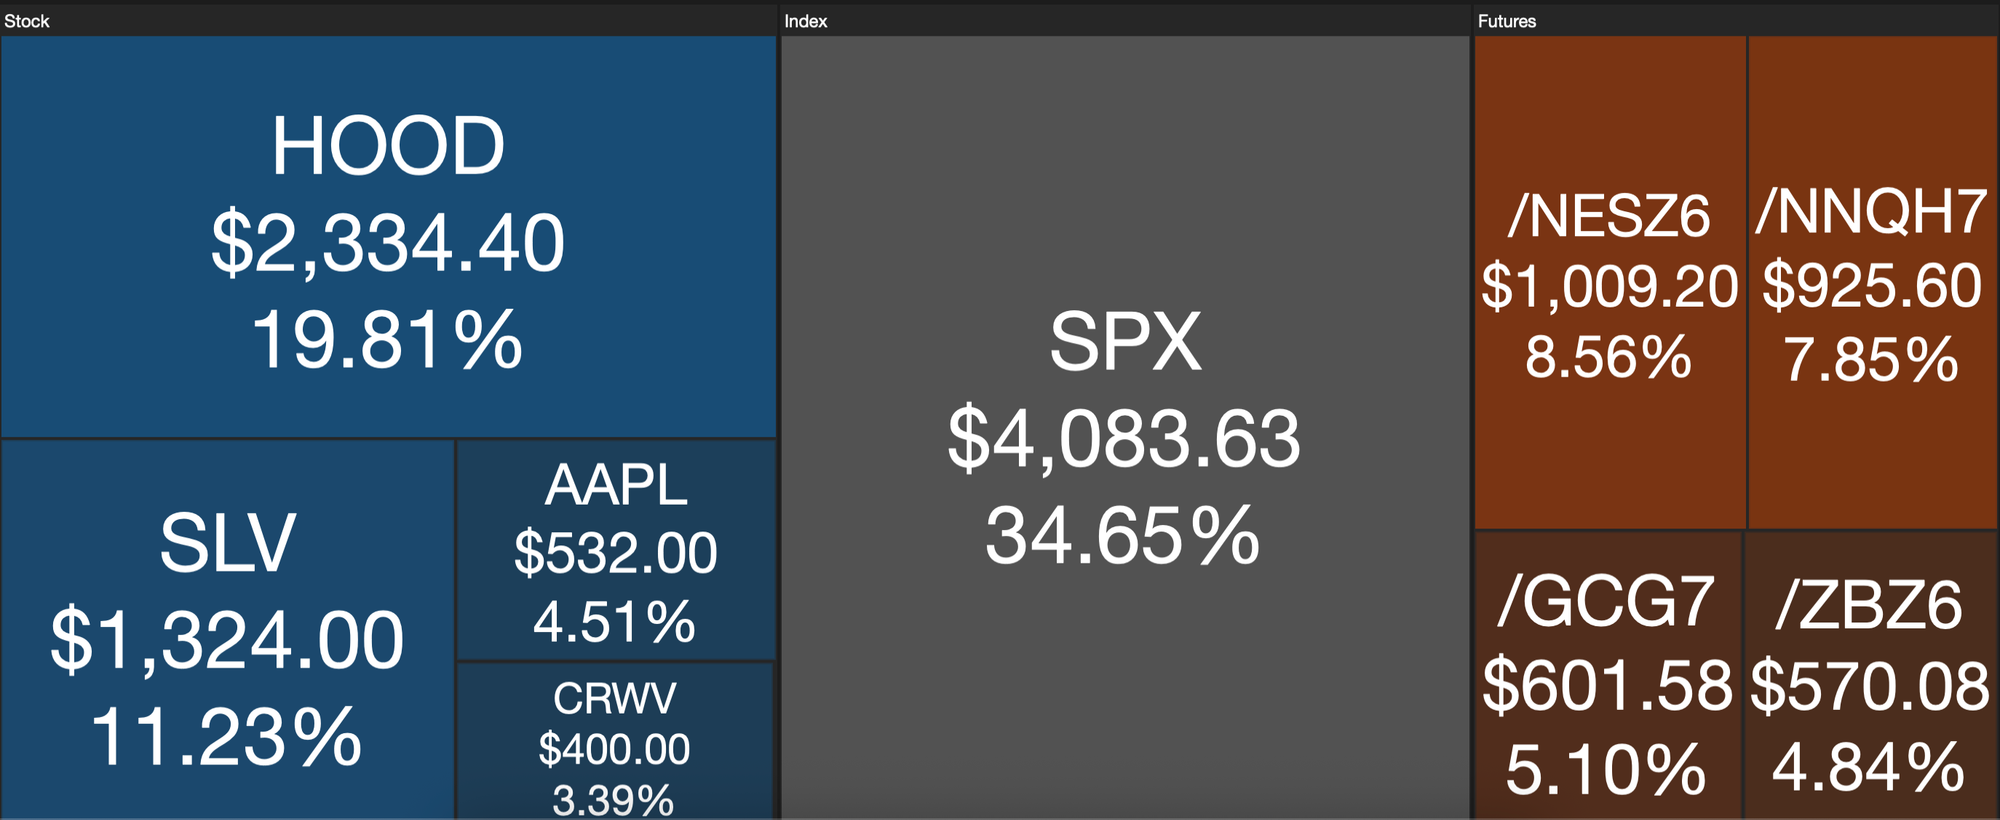
I am leaning bullish. I am long 83 deltas, collecting about $34 a day in theta out of a remaining $6,485 in extrinsic value. At Day 123 I was long 185 deltas.
I have short puts in HOOD, SLV and CRWV, Call Credit Spreads in AAPL, call calendars in RDDT and NOW, and Put Credit Spreads in /ES, gold and /ZB. I am also long two /NES and two /NNQ nano futures. In SPX I have a Nov 20 Iron Condor at 7825/7840 calls and 7345/7330 puts, and a Nov 20 7700/7725 Call Debit Spread paired with a 7375/7350 Put Credit Spread.
Running Threads
NDX. One trade this week, a $112 winner. Since Day 123 it is -$7,162, and -$4,861 for the year after fees.
Single-name hold time. Since Day 123, 40 of 44 single-name trades closed within seven days won. The HOOD Dec 18 $80 put and SLV Dec 18 $46 put I sold on Oct 22 are now eight days old.
SOFI. I sold the 200 shares on Sep 21 for a $1,619 loss. The position is closed.
Afternoon debit spread. 18 of 26 days, $2,867, average debit $436.
Futures. I want to keep experimenting with futures and futures options, sized like my other trades. This week's four /NQ Put Credit Spreads were 200 to 250 points wide and risked up to $4,715 each to collect $410 or less. Now, /NQ spreads stay 50 points wide and /ES spreads 25 wide when offered, which should keep the max loss between $1,000 and $1,250, about what an SPX Iron Condor risks. The micro options are too thin to trade well, so I keep the liquid contracts and narrow the width. Since Day 123, 12 futures option trades have made $199. On Friday I also bought my first nano futures, two /NES and two /NNQ, during the 1.8% drop. They closed the day down $41, and I am looking for them to make me some money anticipating a stabiliztion at current price or a slight bounce in the next couple of weeks.
What's Next
For Zero days, I realized I have a tendency to try and make for a loss by risking a lot more than what I planned to risk. Basically - losses cause me to make sub-optimal decisions, and they typically turn catastrophic. I think I blew out all my profits nearly twice in the last 2 months.
Now with just 2 more months to go in the year - I need to tune how I have been operating to continue to stay green. I am looking to filter out some of the things I have been trying and zoom in on things that seem to be working. I am not sure I have the discipline though, let's see. Here are the 3 main things I will look to stick to for the next few weeks as I look to close out the year.
Aggressive Theta Decay
Zero DTE SPX Iron Condors, $15-wide - these have been an outright winner for me, so of course I want to double down on these going forward!
Classic Theta Decay
With roughly 40 trading days remaining, I want to try to extract a daily theta decay of $50-$100, which should put me on track to make between $2000 to $4000 from the days I trade. I want to remain bullish, but I don't want my deltas to run away and be overly directional, so I plan to aggressively manage my deltas and not wait for 21-DTE mark to claim profits or cut losses.
Position Sizing
My profits keep blowing out because of indulging in bigger sized directional risks - and I have been terrible at picking direction. Most of the trades that have worked for me have been direction neutral, so while I can't stop myself from taking directional bets, I am going to cap their size down so they don't hurt me as much (they would hurt me still!).
Here is the whole year in one table. These are the trades I have closed since January, after commissions and fees.
| Trades | Dollars | |
|---|---|---|
| Winners | 508 | +$58,137 |
| Losers | 160 | -$53,081 |
| SOFI shares sold Sep 21 | 1 | -$1,619 |
| Cash parked in BIL, SGOV and T-bills | +$201 | |
| Net realized | +$3,638 |
I made $58,338 and gave back $54,700 of it. That leaves me about 6 cents out of every dollar my winners brought in. I win more than three trades out of four, but my average winner makes $114 and my average loser costs $332, so every loss erases about three wins. The positions I still hold are down another $1,820, which puts the year at +$1,833.
Then I asked myself what the year looks like without NDX. Here is the same table with every NDX trade taken out.
| Trades | Dollars | |
|---|---|---|
| Winners | 487 | +$52,526 |
| Losers | 144 | -$42,609 |
| SOFI shares sold Sep 21 | 1 | -$1,619 |
| Cash parked in BIL, SGOV and T-bills | +$201 | |
| Net realized, without NDX | +$8,499 |
NDX cost me $4,861 on 37 trades. I won 21 of them, but my average NDX loss was $654 against an average win of $267. Take it out and I keep about 16 cents of every dollar my winners bring in, up from 6. I hold no NDX positions right now, so counting everything, the year would be +$6,694. That is 12.0% on the roughly $56K I have put in, just ahead of SPY's 11.69%. I can't undo it after the fact. But one underlying is the difference between beating SPY and barely clearing my first goal of not losing money. I don't need a higher win rate. I have lost heavily in NDX, and so staying away from it should not only help with the numbers directly, but also keep me in a good headspace to keep making better decisions. I understand it's hindsight, but burning my fingers is how I have learnt this game, and it's a nice way to see "what could have been!"
This might be the second-last post of the year, I want to write one more at the end of the year.
Thanks for reading.
📌 Disclaimer: Nothing on this site is financial advice - I'm just here to entertain! Here's my introduction, my trading philosophy, and some ground rules.